Investing in Clifton Multi-Families in 2026: Cap Rates, Rents, and Where the Cash Flow Actually Is
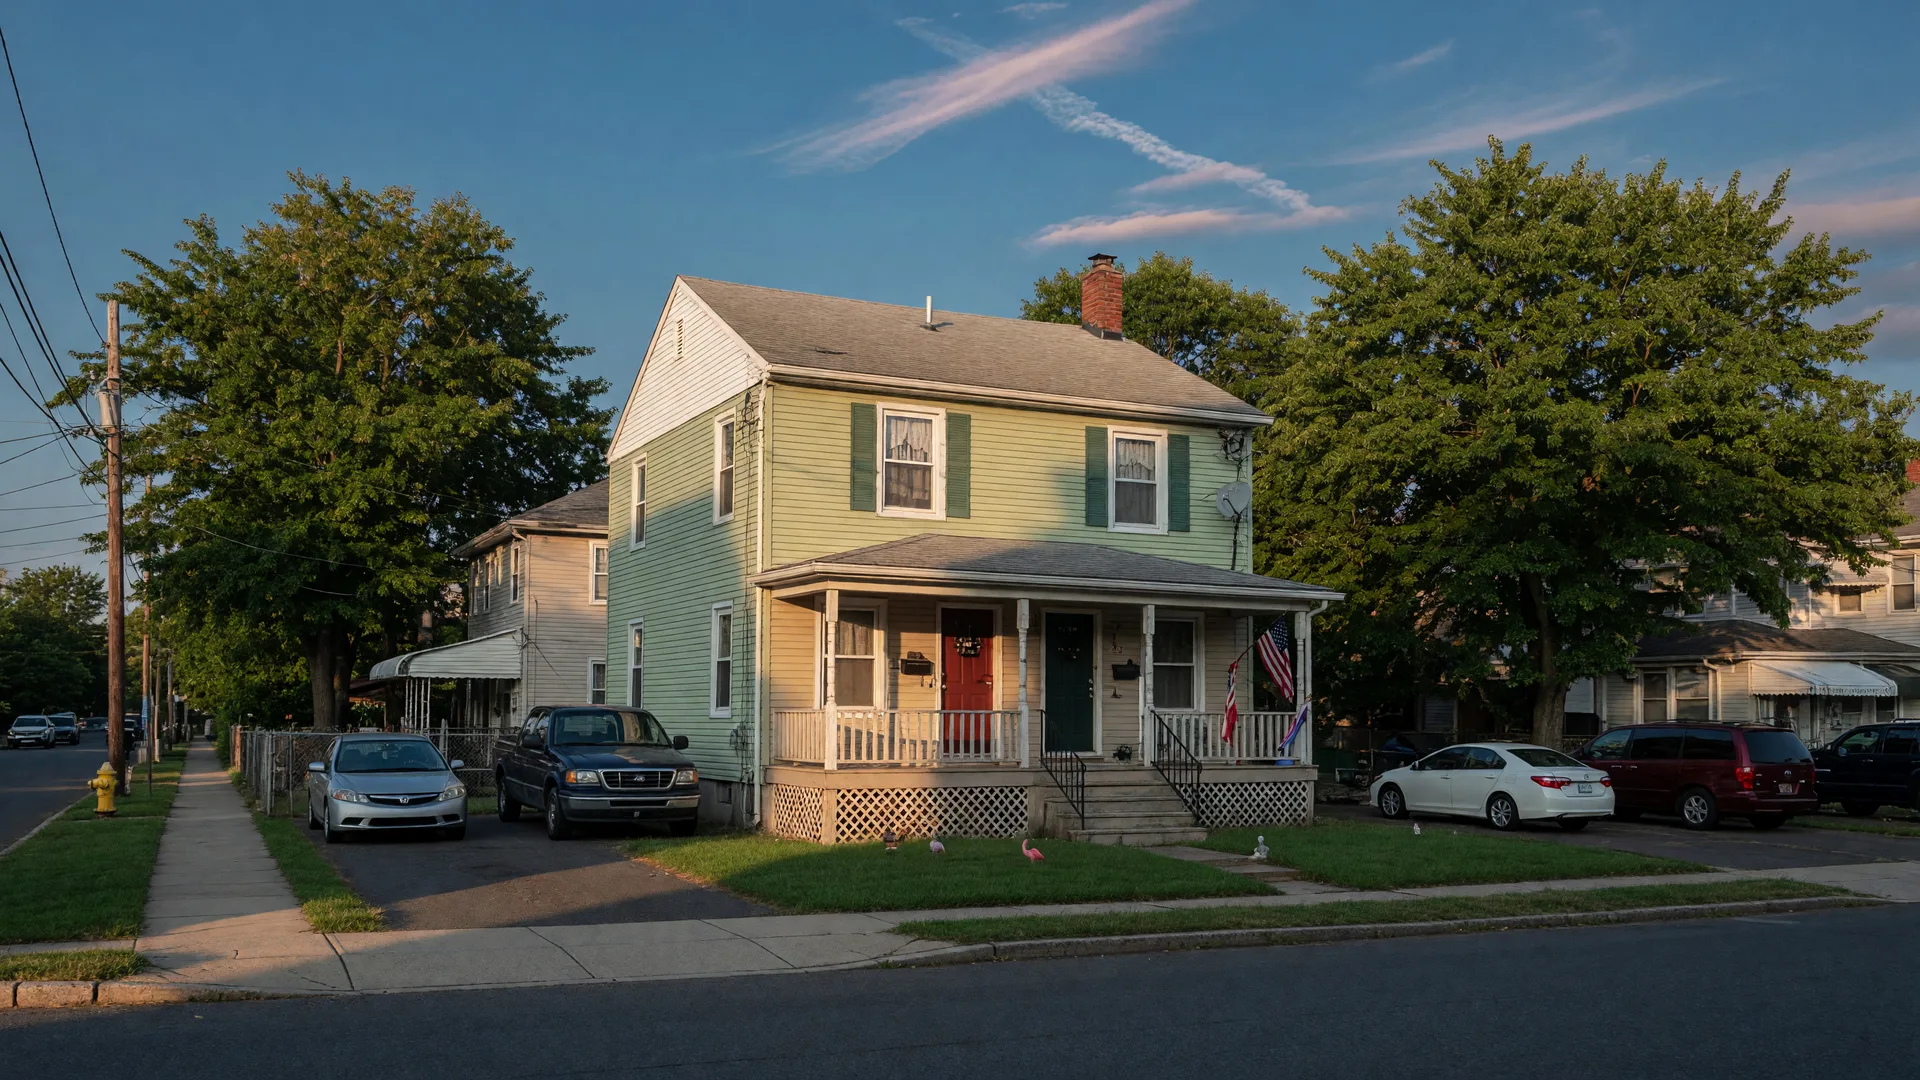
Clifton sits on the Passaic-Bergen county line with rents that behave like Bergen while prices behave more like Passaic, and that gap is the whole investment case. Two-bedroom units in Clifton rent for about $2,600 a month in the current market, $500 to $1,000 above the same unit in Paterson or Passaic, and the two- to four-family stock is the same 1950s to 1970s brick and siding. This post is the 2026 number check on Clifton multi-families: asking cap rates, real rent bands, a cash flow model you can run against any listing, the local rules that shape the math, and the honest truth that most of the money is made at the entry.
Why Clifton Rents Carry a Premium
Location does it. Clifton touches the Bergen County line with Route 3, Route 46, Route 21, and Route 208 minutes away, NJ Transit bus service to the Port Authority, and the big employers of both counties on every side. Tenants can reach the city, the warehouses, the hospitals, and the schools without owning a car. That commute story is why a tenant who pays $1,800 in Passaic will pay $2,600 in Clifton for the same floor plan, and why vacancy runs lower.
Rent premiums like this are rare in North Jersey. They show up where a town sits close to jobs and transit but has not been priced out of reality yet, and Clifton has held that spot for years. Median asking rents across unit types sit around $2,400 a month, one-bedrooms around $1,800 to $2,100, and two-bedrooms around $2,600, so a three-family where every unit is a two-bedroom can gross $7,000 to $7,500 a month. Start there, because that number, verified against what the building actually reports, is the foundation of everything else.
What Cap Rates Look Like in Clifton Right Now
Asking caps on Clifton multi-family listings in 2026 run roughly 5.5% to 7.5%. Smaller two- to six-unit buildings sit at the high end, around 7%, which is where individual investors live. Larger buildings trade tighter: a 14-unit building came to market at a 6.72% cap, a five-family mixed-use at about $2 million listed at 6.67%, and the bigger professional product runs lower still. A 22-unit building at 46 Burgh Avenue closed in August 2026 for $3.75 million, roughly $170,000 a unit, a price that only works for operators who can push rents and hold.
Those are asking caps from listing data, not closed-sale guarantees, so treat them as the starting conversation. On a $650,000 three-family, a 6.75% cap means about $43,875 of net operating income before debt. Whether that number is real depends on one thing: the rent roll, verified on paper with leases, not the seller's word. I walk the full verification in my rent roll guide and in my pre-offer checklist.
The Rent-to-Price Check: Clifton Is One of the Few Towns Where the 1% Test Holds
Old-school investors live by the 1% rule: monthly gross rent at about 1% of purchase price. Most of North Jersey cannot get there. In Clifton, a $675,000 three-family grossing $7,200 a month is a hair over 1%, which makes the town one of the few in Passaic County where the test even holds. But here is the part the rule does not tell you: at today's rates and Clifton property taxes, 1% gross rent still barely cash flows.
Run the Full Cash Flow Before You Commit
Build the model line by line. Take a $675,000 three-family, 20% down, a $540,000 loan at 6.5% for 30 years, and $7,200 of verified gross rent. Back out 5% for vacancy and collection loss, $360. Back out operating costs at 30% of gross: management, maintenance, water, snow, permits, common electric. That is $2,160. NOI before debt: $4,680 a month. Now the debt and tax stack: principal and interest at $3,413, property taxes estimated at $1,200 (pull the real number from the assessment, they vary by block), insurance at $250. Total $4,863. That model cash flows negative by about $180 a month at full list price.
Read that honestly. It is not a reason to skip Clifton; it is the reason the price beats the address. Take the same building at $615,000, ten percent below market, where off-market and rough-condition properties come in, and the monthly nut drops to $4,560. Cash flow turns positive around $120 a month, you bank $60,000 of equity the day you close, and your yield on the $123,000 down payment starts near 40% once you count the forced equity. The full line-by-line model is in my cash flow projections post; run every deal through it before you sign anything.
Where the Below-Market Entries Come From
Off-market in North Jersey means three sources: probate and estate homes, tired landlords ready to exit, and properties with deferred maintenance and month-to-month tenants. That is my lane. As a Certified Probate Specialist, I see estate and inheritance buildings before they hit the MLS, and a large share of my investor clients bought their first North Jersey building from an estate or a landlord who was done. How to find off-market multi-family deals walks the prospecting side; the short version is that consistency beats cleverness: list-serve, network, and ask every estate trustee and tired landlord what they plan to do with the building.
The Local Rules That Shape Every Deal
Three rules matter before you underwrite anything in Clifton. Rent control: Clifton's Chapter 363 limits annual increases on buildings with four or more units, roughly 3% tied to the Consumer Price Index. Two- and three-families sit outside the ordinance, which is why the small multi is the investor sweet spot. My rent control guide maps the Passaic and Bergen rules.
Lead paint: New Jersey's P.L. 2021 c.182 has required periodic inspections of pre-1978 rentals since July 2022, at tenant turnover or every three years, whichever comes first. A lead-safe certificate lasts two years. Budget the inspection and any remediation into the renovation line, because a pre-1978 unit with no certificate does not rent in New Jersey.
Section 8: Passaic County's voucher demand is deep and the housing authority pays on schedule. The trade is inspections and paperwork, but where payment standards track market rents, a Section 8 tenant is steady, predictable income. My Section 8 guide covers when it helps and when it does not.
The BRRRR Truth in Clifton
BRRRR works in Clifton only when the entry is below market, because an investment refinance typically needs 25% down at current rates, and the appraisal has to justify the new loan. You cannot refinance your way out of a deal you overpaid for at list. Buy the estate building at a discount, force the rents with light rehab, and refinance at the higher value to recycle the capital. The strategy is covered end to end in my BRRRR post, but the one-sentence version is this: the refinance only works if the purchase was the deal. The 46 Burgh Avenue sale is the reminder: at $170,000 a unit, that buyer is playing a different game with different capital. Your game is the tired two- and three-family bought ten percent below what the renovated comps say, with a real rent roll and a clear exit.
The Bottom Line
Clifton gives you Bergen-adjacent rents on Passaic County prices, a rare combination in North Jersey, and the small multi-family is the vehicle: outside rent control, meeting the 1% rent test, and deep enough tenant demand to keep vacancy low. The honest math at 2026 rates is that list price barely covers the nut, and the cash flow comes from buying below market, verifying the rent roll, and respecting the lead paint and rent control rules. Deals that meet that bar are not common, and they rarely sit on the open market.
Bring me the address or the offering memorandum and I will pull the comps, verify what the rent roll should be, run the cap rate and the cash flow at today's rates, and tell you straight whether it works. The goal is not just to close, it is to help you win. Talk soon.
Underwriting a Clifton Multi-Family?
I will run the numbers on any North Jersey deal: verified rents, real taxes, cap rate, cash flow at today's rates, and whether the entry price leaves room to win. Free investment analysis, straight answers, no pressure.
North Jersey's AI-Certified Realtor with 15+ years of experience. Specializing in probate sales, short sales, and distressed properties in Passaic and Bergen County.